Home · Business · Sep 24 archive
Bond Market Anticipates Fed Hikes Amid Uncertainty
Confirmed
In Short: Analysts noted that this disconnect in outlook has important implications for the Treasury market. Lori Heinel, global chief investment officer at State Street Investment Management, thinks the Fed will likely cut by early 2027 and hold rates for the rest of the year.
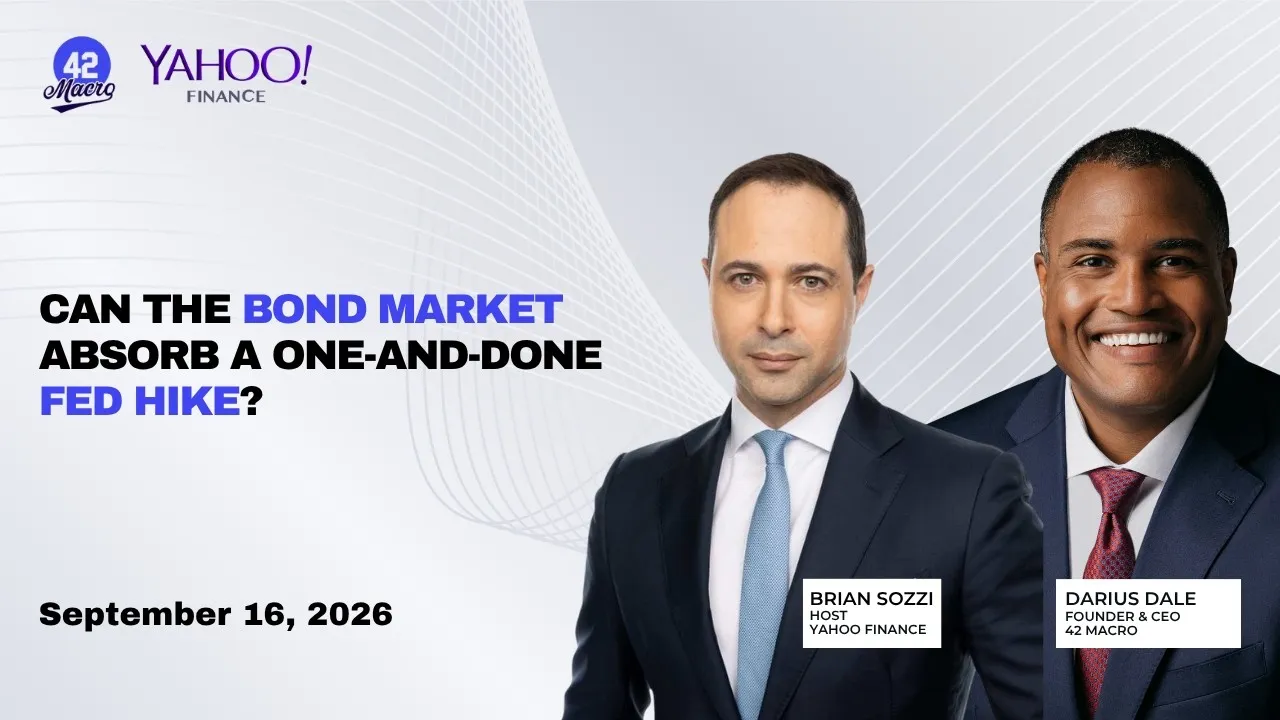
Traders in rate futures are pricing in at least one Federal Reserve hike by early autumn and another next year, according to Reuters. This outlook contrasts sharply with some asset managers who expect the central bank to hold rates steady or cut them as inflation eases.
Analysts noted that this disconnect in outlook has important implications for the Treasury market. Lori Heinel, global chief investment officer at State Street Investment Management, thinks the Fed will likely cut by early 2027 and hold rates for the rest of the year.
Amrut Nashikkar, managing director and head of derivatives strategy at Barclays, noted that without the Fed's clear messaging, markets are increasingly pricing 50-50 outcomes at individual meetings.
The Fed's hawkish rhetoric has flattened the yield curve, unraveling earlier market bets on a steeper curve established before Fed Chair Kevin Warsh took office in late May.
Markets overwhelmingly expect a quarter-point hike, but the Fed’s projections and the bond market’s response may matter more to originators. The Federal Reserve is widely expected to raise interest rates Wednesday after hotter August inflation abruptly reversed economists’ forecasts.
The two-year Treasury yield jumped as markets started pricing in more hikes. Rising energy costs are driving bond yields up, and markets are now pricing a 92 per cent probability that the Fed will raise rates.
With wage growth easing and housing stagnating, Anderson forecasts disinflationary pressure in the coming months, reducing the need to raise rates.
The uncertain inflation path is reflected in the wide divergence in interest rate outlooks among banks. Citi expects the Fed's next move to be a cut, projecting a 25-basis-point reduction as soon as October.
BofA Securities, in contrast, expects three 25-basis-point rate increases this year.
The Fed’s accompanying economic projections brimmed with “hawkish overtones,” which could signal more rate hikes to come, said Jeffrey Roach, chief economist for LPL Financial, in written comments.
The vote was unanimous among the Federal Open Market Committee’s 12 voting members. Markets are now pricing a 92 per cent probability that the Fed will raise rates.
What this adds
The bond market's expectation of rate hikes contrasts with some asset managers who predict steady or lower rates due to potentially easing inflation.
Background
Traders in rate futures are pricing in at least one Federal Reserve hike by early autumn and another next year, according to Reuters. This outlook contrasts sharply with some asset managers who expect the central bank to hold rates steady or cut them as inflation eases.
Daniel Lacalle, an economist and fund manager, argues that rate hikes won't address inflation or debt issues.
What's confirmed
- Traders in rate futures are pricing in at least one Federal Reserve hike by early autumn and another next year, according to Reuters. This outlook contrasts sharply with some asset managers who expect the central bank to hold rates steady or cut them as inflation eases.
- Analysts noted that this disconnect in outlook has important implications for the Treasury market. Lori Heinel, global chief investment officer at State Street Investment Management, thinks the Fed will likely cut by early 2027 and hold rates for the rest of the year.
- Amrut Nashikkar, managing director and head of derivatives strategy at Barclays, noted that without the Fed's clear messaging, markets are increasingly pricing 50-50 outcomes at individual meetings.
- The Fed's hawkish rhetoric has flattened the yield curve, unraveling earlier market bets on a steeper curve established before Fed Chair Kevin Warsh took office in late May.
- Markets overwhelmingly expect a quarter-point hike, but the Fed’s projections and the bond market’s response may matter more to originators. The Federal Reserve is widely expected to raise interest rates Wednesday after hotter August inflation abruptly reversed economists’ forecasts.
- The two-year Treasury yield jumped as markets started pricing in more hikes. Rising energy costs are driving bond yields up, and markets are now pricing a 92 per cent probability that the Fed will raise rates.
- With wage growth easing and housing stagnating, Anderson forecasts disinflationary pressure in the coming months, reducing the need to raise rates.
- The uncertain inflation path is reflected in the wide divergence in interest rate outlooks among banks. Citi expects the Fed's next move to be a cut, projecting a 25-basis-point reduction as soon as October.
- BofA Securities, in contrast, expects three 25-basis-point rate increases this year.
- The Fed’s accompanying economic projections brimmed with “hawkish overtones,” which could signal more rate hikes to come, said Jeffrey Roach, chief economist for LPL Financial, in written comments.
- The vote was unanimous among the Federal Open Market Committee’s 12 voting members. Markets are now pricing a 92 per cent probability that the Fed will raise rates.
What's still developing
- "The market is way too aggressive in pricing rate hikes, mistaking that oil inflation pushing through food prices and everything else will persist," said Byron Anderson, head of fixed income at Laffer Tengler Investments.
- "Warsh made it clear that 'markets work less efficiently' when they reflect the Fed's views back," said Guneet Dhingra, head of U.S. rates strategy at BNP Paribas.
- Know more. ) The FXStreet Insights Team is a group of journalists that handpicks selected market observations published by renowned experts.
- ING’s Francesco Pesole explains that despite political noise in Germany and an additional ECB hike now expected in December, ING keeps its EUR/USD profile unchanged with a 1.160 year-end target.
- He sees similar front-end pricing for EUR and USD, expects dovish repricing on lower energy prices, but highlights mostly downside risks for EUR/USD this week, especially if Brent rises and Fed hike odds increase.
- Since we see only one more hike by both central banks this year and then a prolonged pause, the dovish repricing should be similar in size.
- The Federal Open Market Committee begins its two-day meeting Tuesday and will release its policy decision at 2 p.m.
- Nearly 53% of economists who provided longer-term forecasts expect at least one additional increase by the end of March, while financial markets are pricing in several increases through July 2027.
- The bigger questions for mortgage rates are what Fed officials project for the remainder of the year, how Chair Kevin Warsh characterizes the inflation outlook, and whether the decision reassures or unsettles the long-term bond market.
- The risks to oil prices, however, are still skewed higher, as stockpiles draw down quickly and demand destruction is increasingly the only real lever left to bring the market back into balance.
- Observers expect a 25 bp increase at Japan central bank’s meeting this week, and will be looking for clues about further tightening [TOKYO] The yen’s sharp drop after the US Federal Reserve’s hawkish hike is raising the stakes for the Bank of Japan’s (BOJ) policy meeting on Friday (Sep 18), with strategists warning that the currency could weaken further unless officials convince markets that more tightening is coming.
- Friday’s expected increase would take Japan’s policy rate into estimates of the neutral range, making it unlikely that officials will signal either a 50 bp move or a sequence of back-to-back hikes, according to Maruyama.